
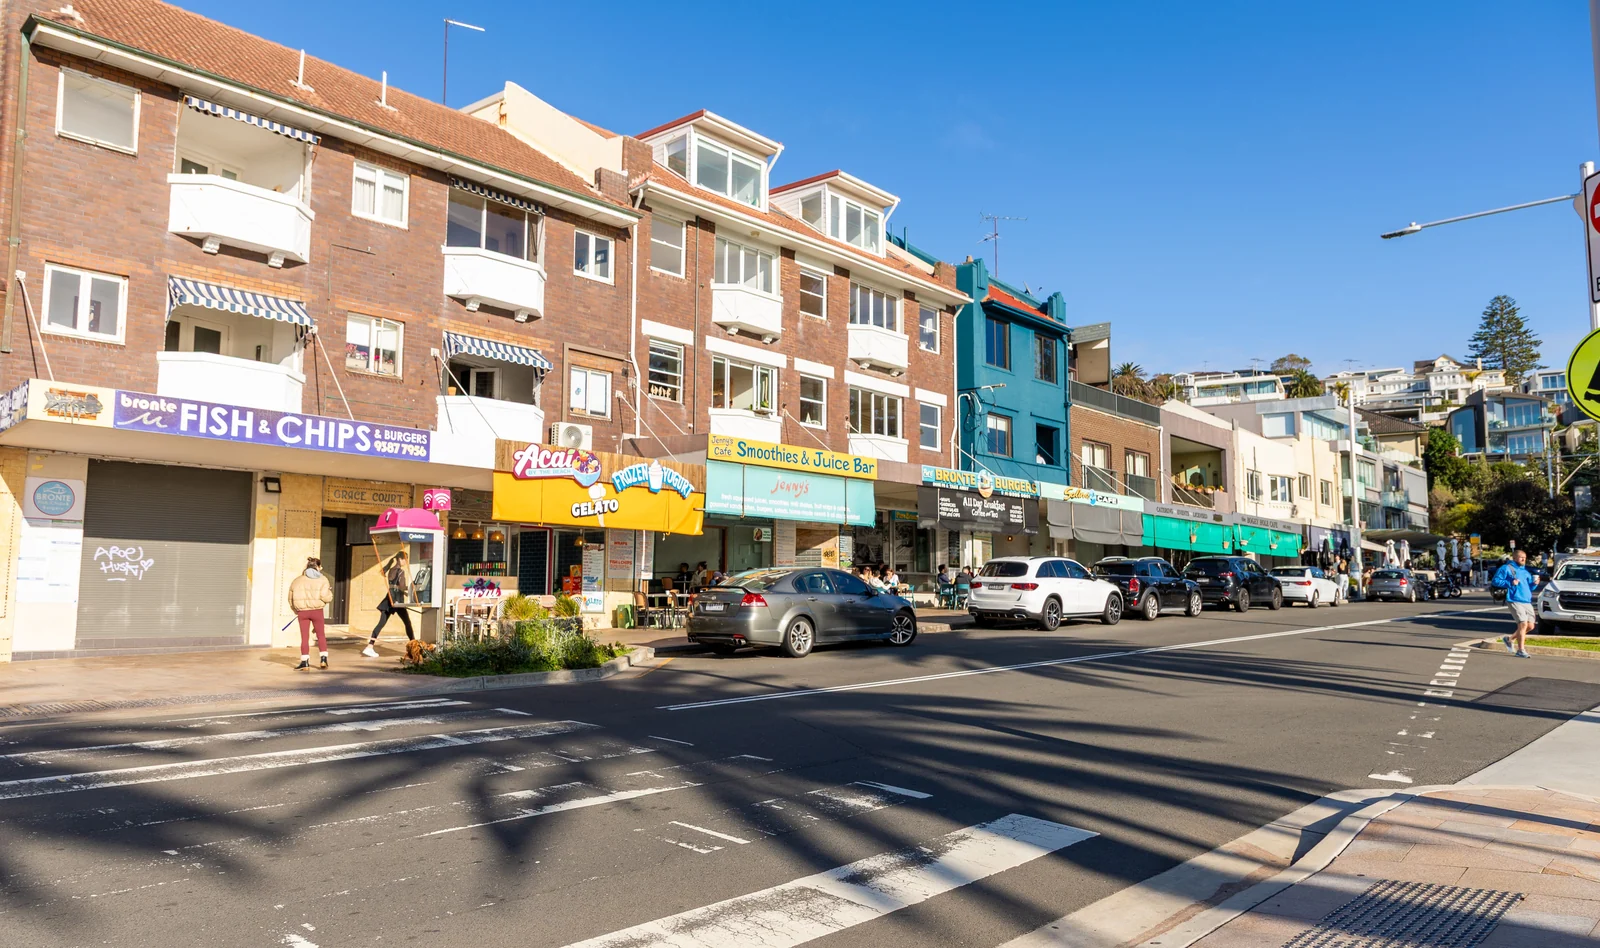
A shop with a flat upstairs can make a lot of sense at the inspection. Perhaps your business could trade downstairs and you could walk home at closing time. Or you see two tenants, two rental payments and a property with more than one use.
Before working out your offer, work out which lending conversation you need. A building you will occupy is a different proposition from one whose tenants must cover the repayments. The finance should follow that distinction, rather than an assumption that bedrooms upstairs make the whole purchase eligible for a home loan.
There are real options to investigate. Pepper Money explicitly includes mixed residential and commercial properties in its commercial lending, while Brighten lists mixed-use among its standard security types. The useful question is which route fits your building, income and plans.
Establish what you are buying
Two front doors do not necessarily mean two properties. A shop and residence can share one title despite separate entrances, meters or tenants. Ask your solicitor or conveyancer to check the title and contract before relying on the ability to sell the flat or refinance the shop separately. Separate loan accounts cannot create separate titles.
Check the approved use, too. A sales listing describing an upstairs residence is not the same as confirmation that it can lawfully be occupied. In NSW, a planning certificate supplies information about zoning, controls and constraints; your adviser can identify the other records needed. Elsewhere, start with the relevant council.
Give the broker the address, title, floor plan and intended use of each part. Ask for a preliminary lender view on the whole property before paying for a valuation or building your budget around an advertised borrowing limit.
If your business will occupy the property
When you plan to trade downstairs, start with the income your business can demonstrate. Living upstairs means that part will not also earn rent. And if your company pays rent to a property-owning entity you control, explain the relationship rather than presenting it as independent tenant income.
Pepper Money's Commercial Property Loan is worth investigating here because its published mixed-use offering includes a one-year tax-return full-documentation option as well as alternative-documentation options. If you have one completed year's return but not a longer set of records, ask your broker to test that route rather than assuming the purchase must wait.
That is an option to investigate, not a promise that one return is the entire application. Ask which supporting financials are required and whether the property and proposed occupation qualify. Where full records are available, request a full-documentation quote too; reducing paperwork is only useful if the price and funding still work.
Pepper also advertises an interest-offset sub-account. If you expect to hold spare cash while running the business, ask how that feature works and what the complete loan costs. A useful cash-management feature can matter over years of ownership, but it should earn its place in the comparison.
Brighten is another option to compare. It lists mixed-use among its standard securities, with Full Doc and Alt Doc routes for owner-occupied or investment borrowing. Full Doc includes a one-year financials option with supporting tax documents; Alt Doc allows a borrower income declaration supported by an accountant declaration as one evidence route.
If your financial records are ready, request the Full Doc assessment. If not, ask which alternative evidence Brighten will accept and what difference that makes to the offer. Have the broker confirm that the proposed product accepts the actual title, use and postcode before commissioning a valuation. The choice should turn on the funding and total cost, not which application has the shortest checklist.
If both parts will be rented out
A fully leased building creates another avenue: lending assessed against the property's rent. Start with the actual leases, their expiry dates, outgoings and payment history. An empty flat or an unsigned shop lease needs to be visible, not counted as dependable income.
For this scenario, ask whether Brighten's Commercial Lease Doc can finance the particular mixed-use building and count both rental streams. Its published mixed-use security acceptance does not settle those product-specific questions. Lease Doc is investment-only, asks for a current lease and statement of assets and liabilities, and requires at least 12 months remaining on the lease. The loan term is subject to the lease term.
That makes the lease dates a practical first check. If the tenancies are close to expiry, or you intend to move into either part, put that on the table before pursuing a rent-led application. Ask for the Full Doc or Alt Doc alternative where your other income needs to support the loan instead.
Turn the shortlist into a purchase budget
Once a lender has considered the property, ask for a written estimate showing the proposed loan, valuation assumptions, fees and net funds available at settlement. Compare those net funds with the price and transaction costs. An advertised maximum is not the amount you can safely put into your contract budget.
Keep cash available for the gap, including the possibility of a lower valuation. Ask your solicitor and tax adviser about duty, any GST treatment and settlement adjustments before treating the purchase like an ordinary home transaction.
For the loan comparison, use the same borrowing amount and expected holding period. Include interest, setup charges, ongoing fees and the cost of repaying early. If you expect to sell the building or change its use within a few years, make that timing part of the quote rather than an afterthought.
The next step is specific: establish the title and occupation, identify whether business income or rent will support the loan, then request the relevant product assessment and a cash-to-complete figure. Bring those details to Flexdoc and ask for a comparison built around the building you are actually buying. Resolve the finance conditions with your advisers before making an unconditional commitment that depends on borrowing.
General information only, not personal credit, financial, legal or tax advice. Sources checked 26 October 2026. Product examples are starting points for assessment, not recommendations for an individual borrower. Terms and availability can change.